

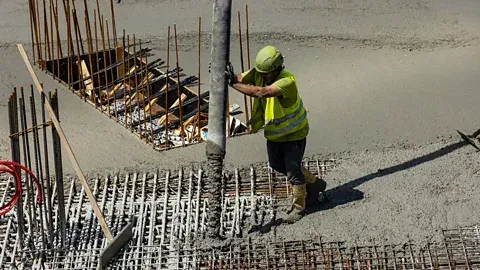
Under the Texas Labor Code, workers’ compensation coverage is generally elective for private employers, and the Texas Department of Insurance says it is not required in most cases. That is only the start of the answer for a concrete company, because contracts, public projects and the consequences of going without coverage all matter.
This post states what Texas records say and attributes each point to the agency or statute. It is not legal advice, and where the records are silent it says nothing.
What Texas statute says about choosing coverage
The Texas Labor Code makes coverage generally elective for private employers, with exceptions for public employers and as otherwise provided by law (Labor Code ch. 406). The Texas Department of Insurance states the same: private employers can choose to carry coverage, and it is not required in most cases, while all governmental entities must have it (TDI).
An employer may obtain coverage through a licensed insurance company or through self-insurance as the statute provides. The Division of Workers’ Compensation, within the Texas Department of Insurance, administers the state system.
What changes if you go without it
An employer that chooses not to carry coverage must notify the Division of Workers’ Compensation in writing and must tell employees whether it has coverage. If an injured employee sues, the employer cannot defend on contributory negligence, assumption of risk or fellow-employee negligence. Those consequences come straight from Chapter 406. How they apply to your business is a question for an attorney.
Public projects and general contractors
On Texas public building or construction projects, the governmental entity must require the contractor to certify in writing that it provides workers’ compensation coverage for employees on the project. A concrete company that bids public work should expect to give that certification.
Private general contractors write their own insurance requirements. Many ask every subcontractor for proof of coverage whether or not the statute does. The what insurance concrete clients require post lists common asks.
Real-World Scenario: A Texas flatwork company with a small crew has always operated without a comp policy. It bids a public school project and learns the contract requires a written certification of coverage for employees on the job. The company has to decide, before the bid date, whether to buy a policy or pass on the work.
Next step. Start a quote and send the insurance section of the contract you are bidding. We bring it to carriers before a policy binds.
Subcontractors and the general contractor
The Labor Code provides that a subcontractor operating as an independent contractor under a written agreement assuming employer responsibilities is not an employee of the general contractor for workers’ compensation purposes. That is a statement of the statute’s text; whether a particular subcontractor meets it is a legal question. The finisher insurance post explains what subcontractors are usually asked to show.
Motor carriers and workplace safety
A registered Texas motor carrier whose primary business is transportation for compensation or hire between two or more municipalities must carry workers’ compensation or TxDMV-approved accident coverage for its employees (Transportation Code ch. 643). Whether a mixer or pumping operation falls in that category depends on how it is organized, and the cement truck insurance post explains the questions to ask.
Texas does not operate an OSHA-approved state plan, so private-sector workplace safety there falls under federal OSHA. That matters for the safety routine a concrete company documents.
Deciding with the contract in hand
Several questions a Texas concrete owner might ask are not answered by the records behind this post: what a policy costs, how a particular carrier treats a small crew, and whether a given business must register with a particular agency for another reason. Those points are left out rather than guessed. Ask your agent, and ask the Division of Workers’ Compensation when a statutory question matters.
The practical test is the contract: if it requires coverage or a certification, the elective rule does not help you bid the job. If it does not, the decision is about risk. If an employer without coverage is sued by an injured employee, the defenses listed above are not available to it. That is the consequence to weigh against the decision.
Read the statute and your contract together, decide with an attorney if there is any doubt, and make sure the policy you choose matches the work. For the broader picture of how comp works for a crew, see the concrete worker insurance guide and the workers’ compensation page.