

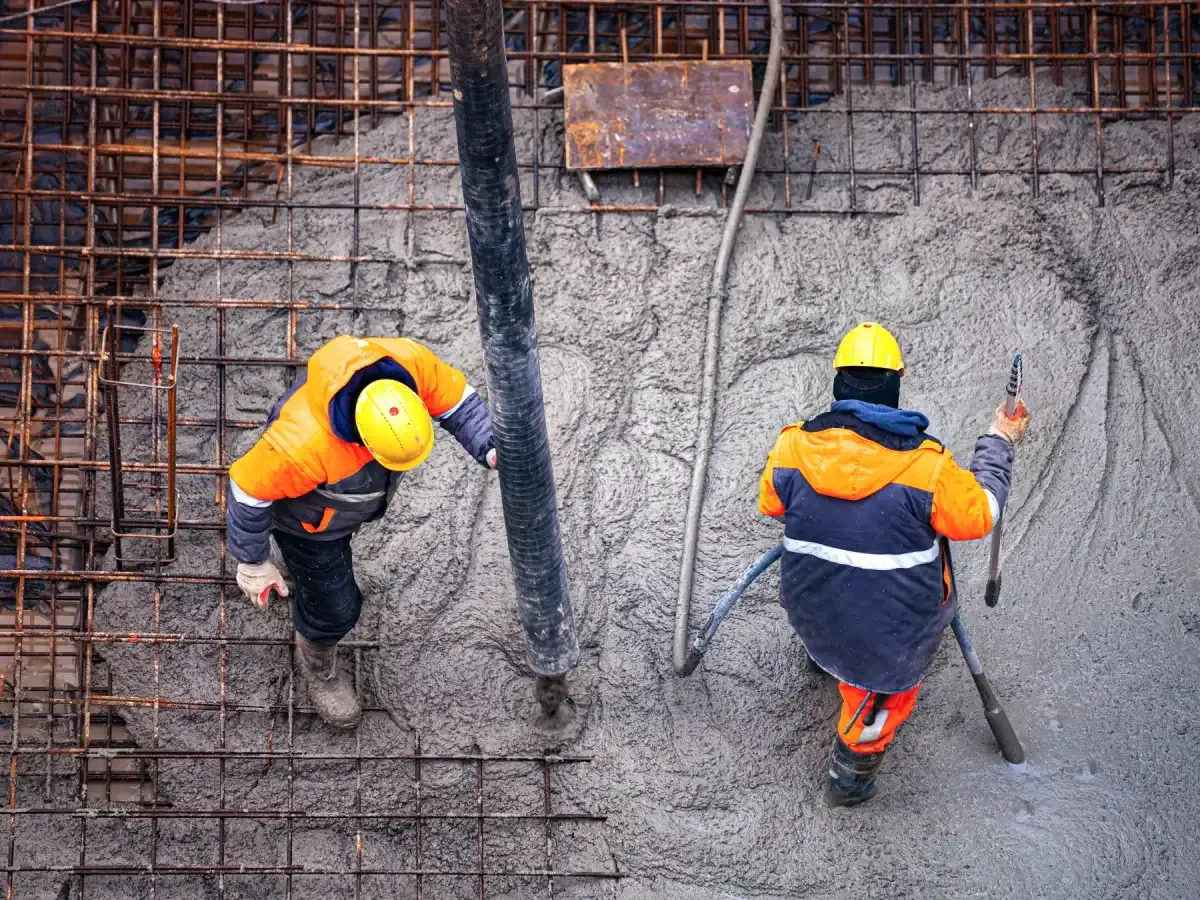
Concrete worker insurance usually means two policies working together: workers’ compensation for injuries to the people on your crew, and general liability for harm the work causes to others. Comp follows payroll and classification, while liability follows the work and the contracts you sign.
This post is for concrete contractors who employ finishers, laborers, form setters and pump hands, and for crew leads trying to understand what their company carries.
What workers’ comp does for a concrete crew
Workers’ compensation is the coverage for work injuries to employees. Concrete is physical work: handling forms and rebar, working around hot loads and chutes, kneeling on wet slabs and standing near moving equipment. The workers’ compensation page explains the structure, and this section is the plain version.
Whether a business must carry comp, and how, is set by each state. In Texas, for example, the Texas Department of Insurance says private employers can choose to carry workers’ compensation and it is not required in most cases (TDI). Other states require it of nearly every employer. Check your state before you assume.
On most jobs the crew includes laborers, finishers, form setters, operators, truck drivers and sometimes pump hands. Carriers assign payroll to a classification based on the work performed, and a company with a finishing crew and a pumping truck can have more than one.
Two things drive the comp conversation: whether someone is an employee under your state’s law, and which classification their pay belongs in. Whether a particular person is an employee is a legal determination for the state and the facts. The policy follows those facts, and a payroll report that does not match the work is the usual source of audit surprises.
What general liability adds for the same crew
General liability covers third-party bodily injury and property damage from your work and operations. It is the policy a general contractor’s insurance section asks to see, usually with additional-insured wording. The additional insured post explains the CG 20 10 and CG 20 37 forms, and the completed operations post covers the slab or footing that fails after the crew leaves.
General liability does not pay for your own crew’s injuries. That is the comp policy’s job.
Real-World Scenario: A finishing crew works a commercial slab for a general contractor. A laborer is hurt when a board gives way, and a passer-by later claims dust and debris damaged a parked vehicle. The laborer’s injury runs through workers’ compensation. The vehicle claim runs through general liability. Both policies are needed because they answer different questions.
Next step. If you are not sure your crew, classifications and certificates line up, start a quote with your payroll by role and the contracts you work under. We bring it to carriers before a policy binds.
What a certificate request asks about your crew
Contracts commonly ask for a certificate of insurance listing general liability and workers’ compensation, often with additional-insured status and a waiver of subrogation. The certificate summarizes the policy; it does not change it. Endorsements have to be attached to the policy for the certificate to say what the contract requires.
The what insurance concrete clients require post goes deeper on the buyer side of that request.
Safety, return to work and the next renewal
A workers’ comp policy is renewed on the record the crew builds. Toolbox talks, equipment checks, protective gear and a routine for bringing an injured worker back to modified duty all show a carrier that the owner manages the exposure. None of that settles a price, but it gives an agent something to point to when the renewal conversation starts.
Common gaps on concrete crews
- Payroll described by one title when the work crosses classifications
- Subcontracted labor without certificates of their own
- Additional-insured wording that covers ongoing work but not completed work
- Comp assumed for owners or family members without checking the state rule
- Trucks used by the crew but not scheduled on the auto policy
Accurate payroll, current certificates and a documented safety routine do more to keep a program steady than shopping for a price. The experience mod post explains how the loss record flows into the next renewal, and the post on reducing concrete workers’ comp costs covers what an owner can control.
If you want a second opinion on how your crew is written, send the details through the quote form. We write concrete, so the questions will be the ones a concrete underwriter asks.